Merchant Override Decline: Meaning, Causes & Fixes


A merchant override decline happens when the customer's issuing bank approves the card, then the merchant's own bank or payment processor blocks the charge anyway. The block comes from the merchant's side of the transaction.
I've assembled representment evidence for disputes on my own stores, and the first thing I check before touching a dispute is which bank actually said no. When it turns out to be an override decline, someone has usually spent 1 day already blaming the customer's card.
Knowing which bank rejected the payment tells you who to call. Most of these get fixed in one conversation with your processor.
Key takeaways
What is merchant override decline?
A merchant override decline is when a merchant's bank or payment processor blocks a transaction the customer's card issuer already approved. The name tells you where the block came from. Your processor cancelled an approval the customer's bank had already given.
Your processor can do that because your own bank checks the charge after the issuer does. When a customer pays, their bank checks the card and approves it. The money then passes through your bank, which runs its own checks before anything settles.
Your customer just sees a declined card, same as any other.
You're the one who has to call the processor, and that sends you to your own dashboard rather than to the customer.
What is an acquirer in payments?
The acquirer is the bank or processor that holds your merchant account and settles card payments for you. If you take payments through Stripe, Shopify Payments, or a traditional merchant account provider, that company is your acquirer.
Your acquirer runs its risk checks after the issuer approves. That's where a merchant override decline starts. It looks at your account balance, scores the charge for fraud, and applies the limits tied to your business type.
Any one of those checks can stop a charge the customer's bank was happy with.
What causes merchant override declines?
Your processor blocks these charges over your account balance, a card verification rule, a fraud score, a stale card on file, or your business category code. Those five causes cover the common cases, and a different party fixes each one:
- Insufficient funds in your processor account or reserve
- Expired card on file in your own billing system
- Card verification failure against your processor's CVV or address rules
- Fraud detection flags raised by your processor's risk scoring
- MCC restrictions tied to your business classification
The same five causes, with what each block means and who fixes it:
Only one of the five is about fraud, so check the other four before you go hunting for a fraud problem you don't have.
1. Insufficient funds
Your processor account lacks the balance or reserve to cover the transaction. Merchants misread this one most often, because those words usually describe a customer's problem rather than yours.
Many processors hold a rolling reserve.
That's a share of your sales they keep back for a set period, to cover future refunds and disputes. Others ask you to keep a minimum balance instead.
When your balance drops below what your processor requires, it stops settling new charges.
2. Expired card on file
Your system has an outdated expiry date stored for a saved payment method, even though the customer's real card is current. You see this on card-on-file charges, because nothing asks the customer to re-type details they entered months ago.
Banks reissue cards on their own schedule. Unless something updates your stored record, your system keeps sending the old expiry date. Recurring billing gets hit hardest, because those charges keep reusing a stored card across reissue cycles.
An account updater service fixes this. It pulls reissued card details from the networks into your billing system.
Without one, the same batch of declines comes back every reissue cycle.
3. Card verification failure
Your processor's CVV or address check fails and blocks the charge, even after the issuer approved it. Those are two separate checks, and your processor decides its own outcome.
Most processors let you decide how strict to be. You can decline on a CVV mismatch, on an address mismatch, or on both. A tight setting rejects charges the issuer was willing to accept.
That's usually a fraud control someone turned on deliberately. Open your processor's verification rules and check which of those three mismatches you're declining on.
4. Fraud detection flags
Your processor's own fraud system scores the transaction as risky and stops it. These tools watch your whole account, where the issuer only sees the card.
They look at velocity, meaning how many attempts hit your account in a short window. They also read device and IP signals, and compare the order to your account's own history.
A real order trips these when it looks unusual for your business, like a sudden spike after a promotion.
5. Merchant category code (MCC) restrictions
Your merchant category code (MCC), the four-digit code classifying your business type, is restricted for that card or account type. The block is about how your business is classified, so the same charge fails every time.
Some card programs only pay out to an approved set of MCCs. Corporate cards, prepaid cards, and benefits cards are the usual ones.
Take a card issued for medical expenses. It won't pay a general retail code, however ordinary the purchase.
Ask your acquirer to confirm your MCC matches what you actually sell. A misclassified account keeps producing these declines until someone corrects it.
Consequences of merchant override declines for merchants
Every merchant override decline costs you a sale the customer's bank had already approved, and a run of them makes your account look riskier than it is. You lose the revenue right away. You won't spot the pattern nearly as fast.
Your processor holds the decline reason, so your own dashboard often just says "declined" with nothing pointing at your processor.
I've watched merchants spend days chasing customers about cards that worked fine.
One override decline is a rounding error.
Leave a stale verification rule or an outdated MCC in place, though, and your processor keeps rejecting good orders every day. Your acquirer watches your decline rate climb. That's when it raises your fees or puts your account under review.
Handling merchant override declines
Pull the decline reason from your processor dashboard, match it to one of the five causes, then fix that cause before you retry. A second attempt does go through once the cause is gone. Run the same charge against an unchanged rule and you'll get the same decline.
Start with the dashboard, not your storefront, which rarely gives the real reason. Then match what you find against the five:
- Expired card on file goes to your billing system, and you can fix it yourself
- Card verification failure is a settings change in your processor account
- Insufficient funds, a fraud hold, or an MCC restriction goes to your acquirer's support team
Ask that team to confirm the block reason on a specific transaction ID, which beats describing the symptom. Knowing your CAID number before you call saves another round trip.
Some cases won't get sorted out in a support call.
Beyond those five causes, your processor can flag the whole account as over its risk limit, and then no retry works until it lifts the flag. Ask your risk team which threshold you crossed and what they need to see before they raise it. That one can take weeks.
A vague billing statement descriptor creates the disputes that push an account toward those limits. Run one test charge on your own card and read the descriptor as it lands on the statement. It should show the storefront name your customer will recognize.
Merchant override decline vs. issuer decline
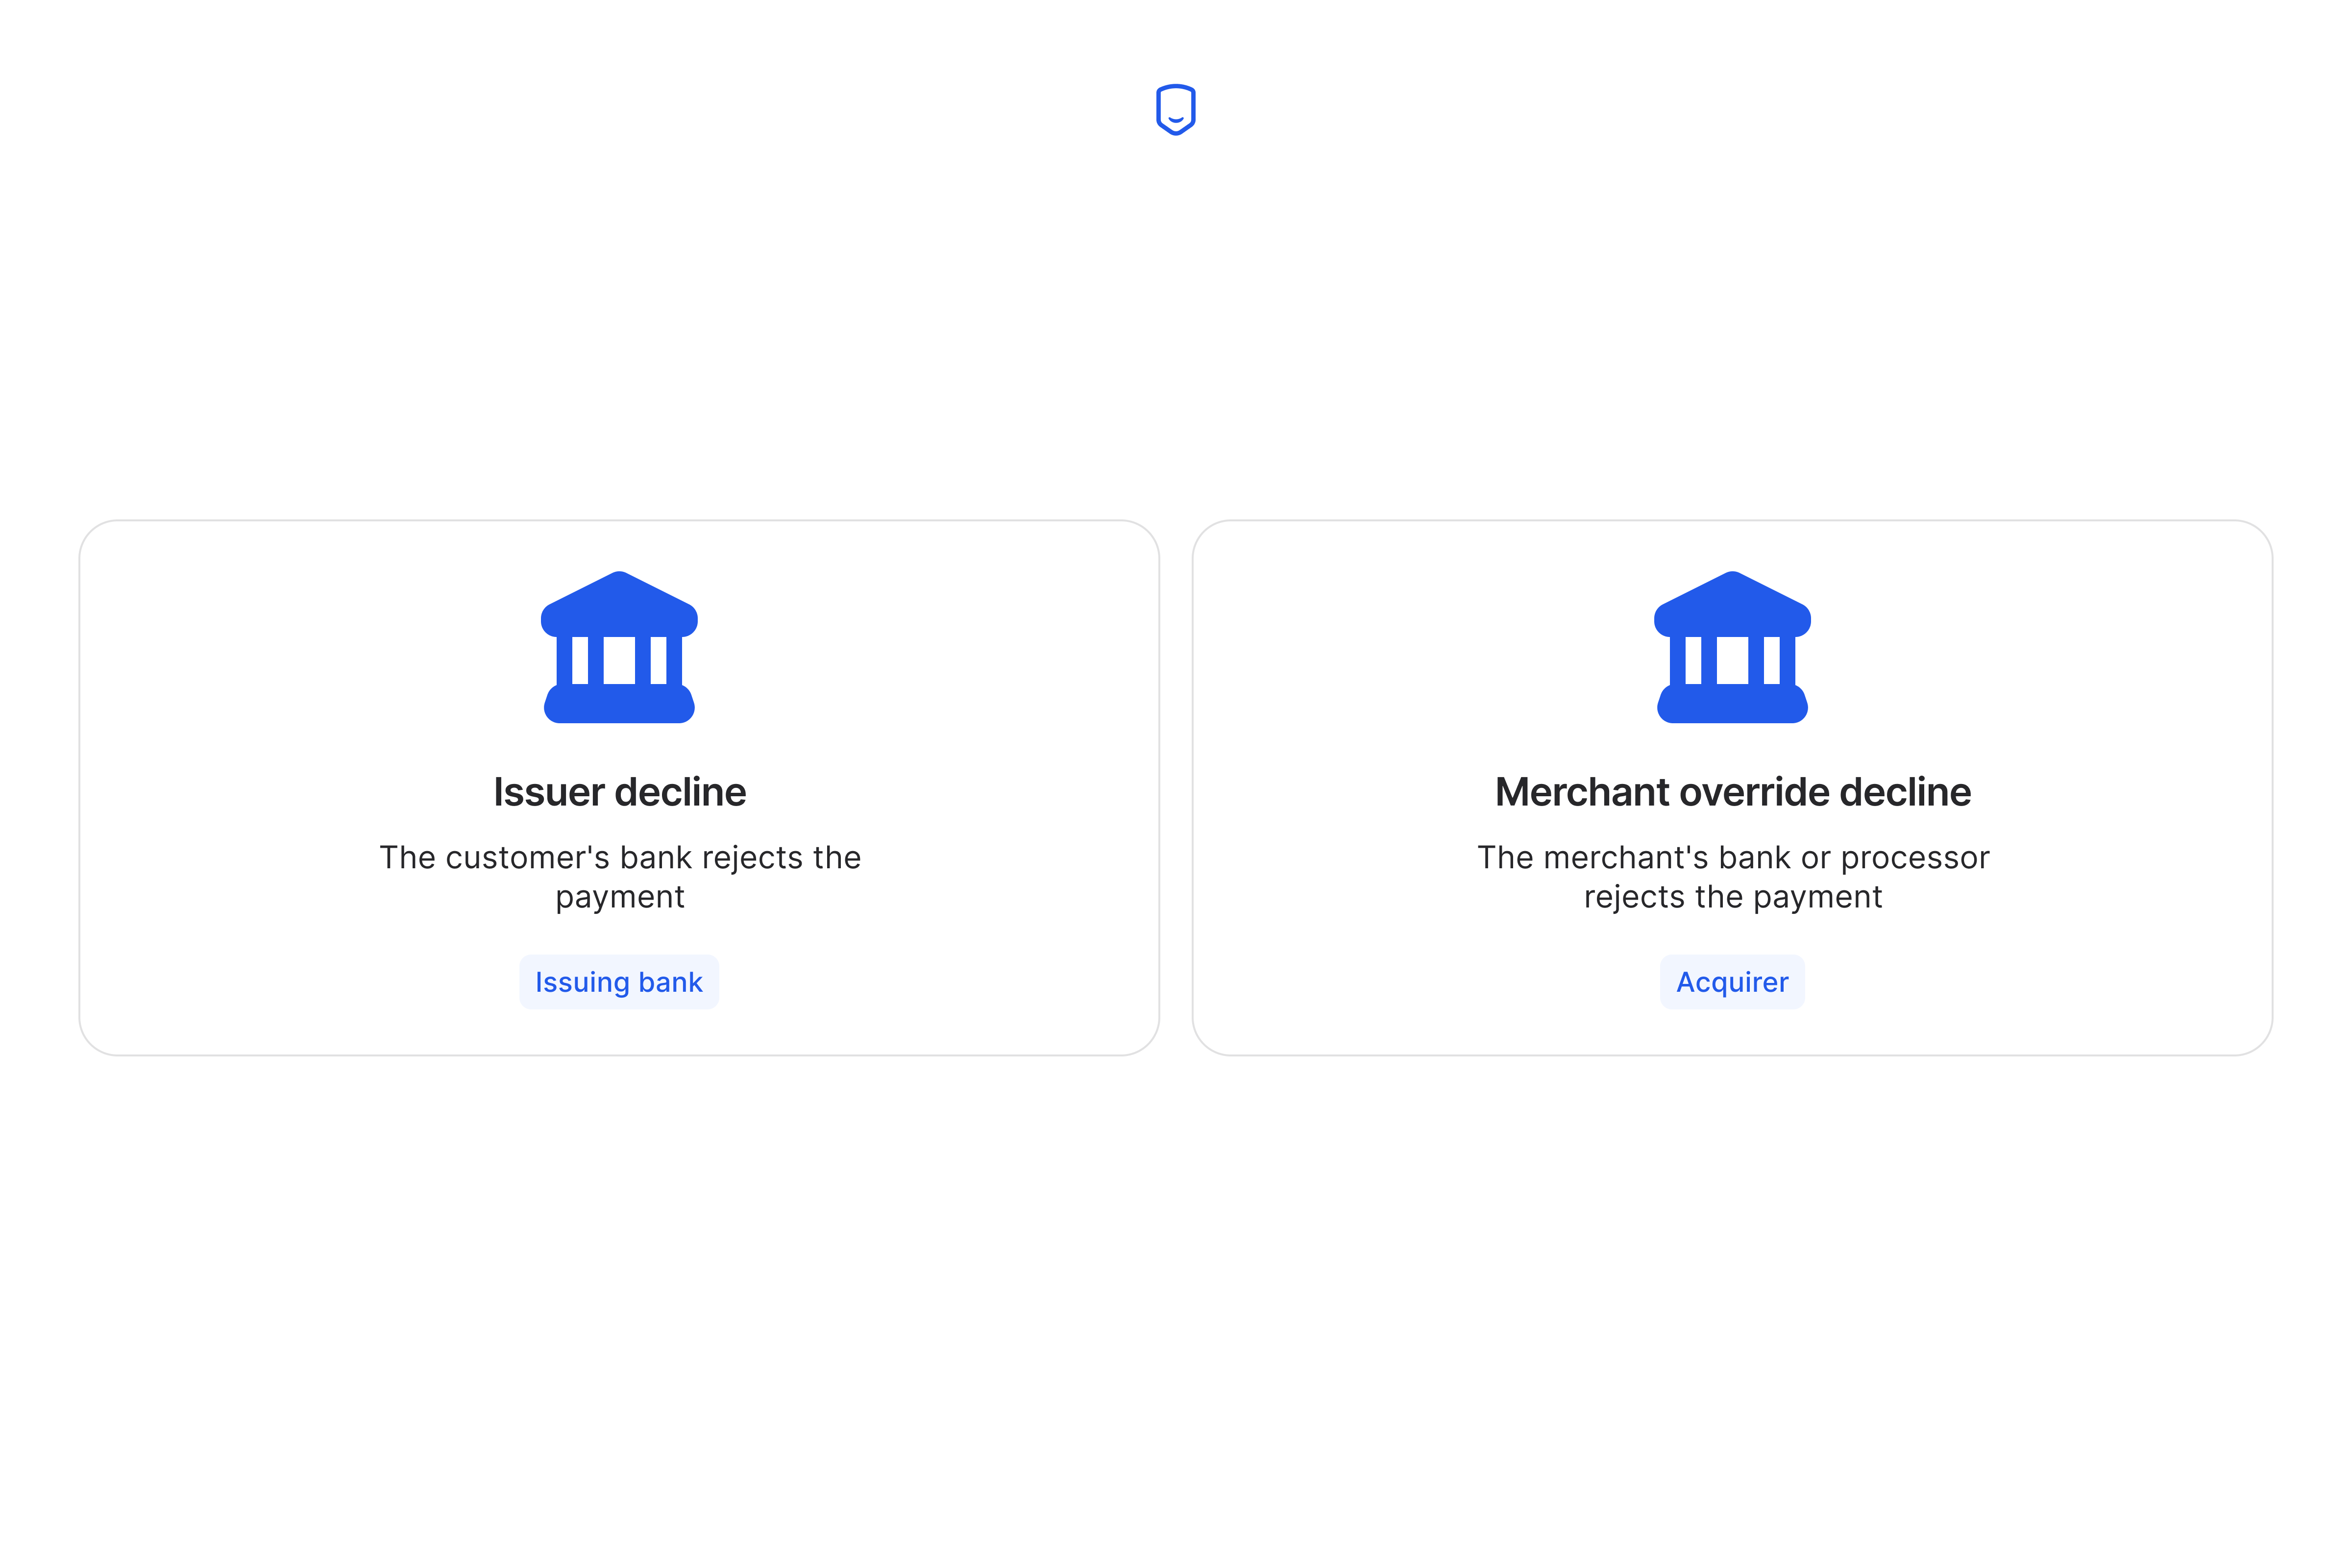
An issuer decline comes from your customer's bank, and a merchant override decline comes from yours. Those are the two types of transaction decline. Same result on the checkout page, two different banks, two different fixes.
They also happen at different moments. An issuer decline comes first, when the customer's bank refuses the authorization outright, so the payment never reaches your processor. A merchant override decline lands after that approval has already cleared.
This is also where merchants get it wrong. Both look identical from the customer's seat, so they escalate to the cardholder's bank and lose a day on a call that was never going to help.
Checking which bank declined takes a minute and saves you that day.
What is an issuer decline?
An issuer decline is when the customer's card-issuing bank rejects the transaction and returns a code explaining why. The bank makes that call at authorization, before your acquirer is involved.
Issuers use standard network decline codes. The common ones cover insufficient funds on the actual card, an expired card, a suspected-fraud hold, or a flat refusal to honor the charge. Those codes tell you whether a retry has any chance, and our reason code lookup explains what each one means.
A decline code and a chargeback reason code are two different things. The chargeback process only starts after a payment goes through and the customer disputes it.
FAQ
Do override declines count toward my chargeback rate?
Your chargeback rate counts chargebacks against processed transactions, and a declined charge became neither. A pattern of declines still draws the same acquirer attention that a rising chargeback rate does.
Can I dispute a merchant override decline?
Raise it with your processor's support team as a configuration problem, which is the only route open here. A dispute process exists for money that already moved, and a declined charge never settled.
Should I tell the customer their payment was declined?
Tell them the payment didn't go through and that you're fixing it on your end, without asking them to call their bank. Their bank already approved the charge, so sending them there wastes their time and yours.
Will the customer see a pending charge on their statement?
Sometimes, because the issuer's approval can place a temporary authorization hold before your processor blocks the settlement. That hold drops off on its own, typically in 2-10 days depending on the issuer, and no money leaves the account.
Is an override decline a soft decline or a hard decline?
Soft and hard describe whether a retry can ever work, and an override decline runs either way depending on the cause. A stale card or a one-off fraud flag clears once fixed, while an MCC block stops every attempt until your acquirer changes the account.
Do these hit recurring billing harder than checkout?
Recurring charges take the worst of it. They reuse a stored card and fire on a schedule with nobody watching, where a checkout decline gets spotted while the customer is still there.
Will switching payment processors stop them?
Switching helps when the cause is a limit your current processor sets, like a reserve requirement or an MCC it won't support. Your own stale card data and verification rules follow you to the new one.