How Often Do Merchants Win Chargeback Disputes? (2026 Data)


US merchants win about 54% of the chargebacks they represent. The rate drops by country, to 49.1% in the UK and 36.9% in Brazil. Company size matters too, since large enterprises clear a majority of their cases 52% of the time, against 36% for mid-market sellers.
When I worked chargeback support, merchants lost winnable disputes every week. They'd answered what they thought the customer meant, when the reason code asked something narrower. Read this once and you'll know which number to plan against.
Key takeaways
Rather not fight them at all? Catch disputes before they file.
How often do merchants win chargeback disputes?
US merchants win an average of 54% of the chargebacks they represent, according to Mastercard-sponsored research from Datos Insights. Our guide to disputing a chargeback gives that figure fuller treatment, alongside what it costs to fight one.
Read that 54% for what it is. It covers US merchants only, across every industry and company size the study sampled. Two sellers with identical losses can report very different rates, depending on which cases they chose to fight.
The figure also stops being useful the moment you leave the US, where merchants win meaningfully less often.
A single global average is the wrong thing to plan against.
Does win rate vary by country or company size?
Where you sell and how big you are both move the odds, and the two cuts measure different things. Datos Insights' survey of 840 midsize and large merchants across four countries in late 2024 is the source for both. The country cut is an average win rate, so it runs from 54% in the US down to 36.9% in Brazil.
Here is how the four countries compare:
Bigger sellers win more because they staff for it. A merchant with a dedicated disputes team saves delivery confirmations and checkout messages as a matter of routine, so the evidence already exists when a case arrives. A mid-market team builds the same packet from scratch, under deadline, between other work.
Both cuts come from merchants reporting on themselves, and the Datos Insights survey covered companies above $100m in revenue.
Use the row matching your country and revenue band as a starting target, then adjust against your own results.
Why do issuers and merchants see win rate differently?
Issuing banks claim a 75% win rate while US merchants claim 54%, so the two sides score the same disputes on scales that can't both be right. The Datos Insights research carries that gap without a reconciliation.
The likeliest explanation is that each side counts a different denominator. A bank can count every case that ended with the cardholder keeping the money, including the ones no merchant ever answered. A merchant counts only the cases it fought and got paid on.
Score the same pile of disputes two ways and you get two honest, incompatible percentages.
That matters when your acquirer quotes you a benchmark. Ask which cases the number covers before you measure yourself against it.
Write down which cases you count as fought and which you count as won. Measure against that definition only, because the data that would settle the gap stays private.
What is a chargeback win rate?
Chargeback win rate is the share of the disputes you fought that ended in your favor, found by dividing chargebacks won by chargebacks fought and multiplying by 100.
Both halves of that ratio count only contested cases. "Fought" means you sent representment evidence and the case went to a decision. A chargeback you accepted, refunded, or let lapse stays out of the calculation on both sides.
That is what separates this number from chargeback rate, the measure of how many disputes you get per transaction.
Say you fought 75 chargebacks last quarter and won 30 of them. Dividing 30 by 75 gives 0.4, so your win rate is 40%.
A high rate on a thin sample says less than it appears to. Fight only the three most obvious cases each month and you can hit 90% while writing off everything genuinely contested. Read the rate next to the count of cases behind it.
What factors influence whether a merchant wins?
Your evidence, the transaction type, your fraud tooling, your response speed, and what you sell decide most outcomes.
Here they are in full:
- Evidence provided: whether your documents answer the cited reason code.
- Nature of the transaction: how provable the sale is on paper.
- Fraud prevention system: what you stopped before it became a dispute.
- Timeliness of the response: whether you filed inside the window.
- Type of business: what proof your product category can generate.
1. Evidence provided
The issuer weighs only the part of your evidence that answers the reason code it cited. Your file goes up against one specific question, so evidence aimed at a different question carries no weight, however thorough it looks.
A fraud claim asks whether the cardholder authorized the purchase. Authorization data, a device and IP match, and prior undisputed orders on the same card answer it. Proof of delivery misses, because the parcel's arrival was never in question.
Our rebuttal template walks through which document answers which code.
Volume works against you here. A reviewer working through a queue reads a short packet aimed at the cited code more carefully than a thick one that buries it.
2. Nature of the transaction
Card-not-present sales are harder to win than in-person ones, because your proof is limited to what you captured at checkout.
A chip transaction leaves a record that the card and often the cardholder were present. An online order leaves an address, an IP, and whatever you saved at checkout.
Digital goods sit at the hard end of the same problem. Your proof for a download is the access log, the license activation, or the session record. That works only if you kept it.
Higher-value orders draw more scrutiny too, since they are the ones fraudsters target and the ones issuers examine most closely.
3. Fraud prevention system
Fraud tooling raises your win rate by removing the disputes you were never going to win. Fraud-coded chargebacks are the hardest category to overturn, so the cases you block at checkout never enter your ratio.
Address Verification Service and CVV checks screen the mismatches at authorization.
3D Secure goes further. When a transaction clears with 3D Secure, liability for fraud moves to the issuer, so the chargeback usually cannot reach you at all.
Turn 3D Secure on in your gateway for orders above your average order value first, where the exposure is concentrated.
4. Timeliness of the response
Missing your response deadline loses the case outright, whatever your evidence shows. Card networks set a fixed window per dispute stage, and nobody reads a submission that arrives after it closes.
Your processor's internal cutoff lands days before the network's, because it needs time to package and forward your file. That earlier date is the one that binds you. Find it in your processor's dispute documentation and diary against that date.
Speed helps beyond the deadline. Pulling the records while the order is fresh gets you the customer emails and delivery scans that are hardest to rebuild weeks later.
5. Type of business
What you sell decides what evidence you can produce, and that limit affects your win rate before a single dispute arrives. A physical-goods seller can produce a tracking scan and a signature, and a subscription business disputing a renewal has a billing record and a login history.
Service businesses have the thinnest paper trail of the three, because proof that the work satisfied the customer usually amounts to a set of messages.
Build a signed scope of work and a written completion confirmation into the job itself.
This is also why the category benchmarks you see quoted rarely transfer. Someone else's win rate reflects the evidence their product generates.
Chargeback win rate vs. net recovery rate
Win rate counts only the disputes you fought and won, while net recovery rate counts the disputed revenue you keep after fees and staff hours. Net recovery is always lower, because win rate counts only the cases you chose to fight and net recovery counts every chargeback you got.
Three things pull the second number below the first:
- A dispute you left alone still cost you the money.
- A case you won can return as a second chargeback.
- Every chargeback carries a fee you pay either way.
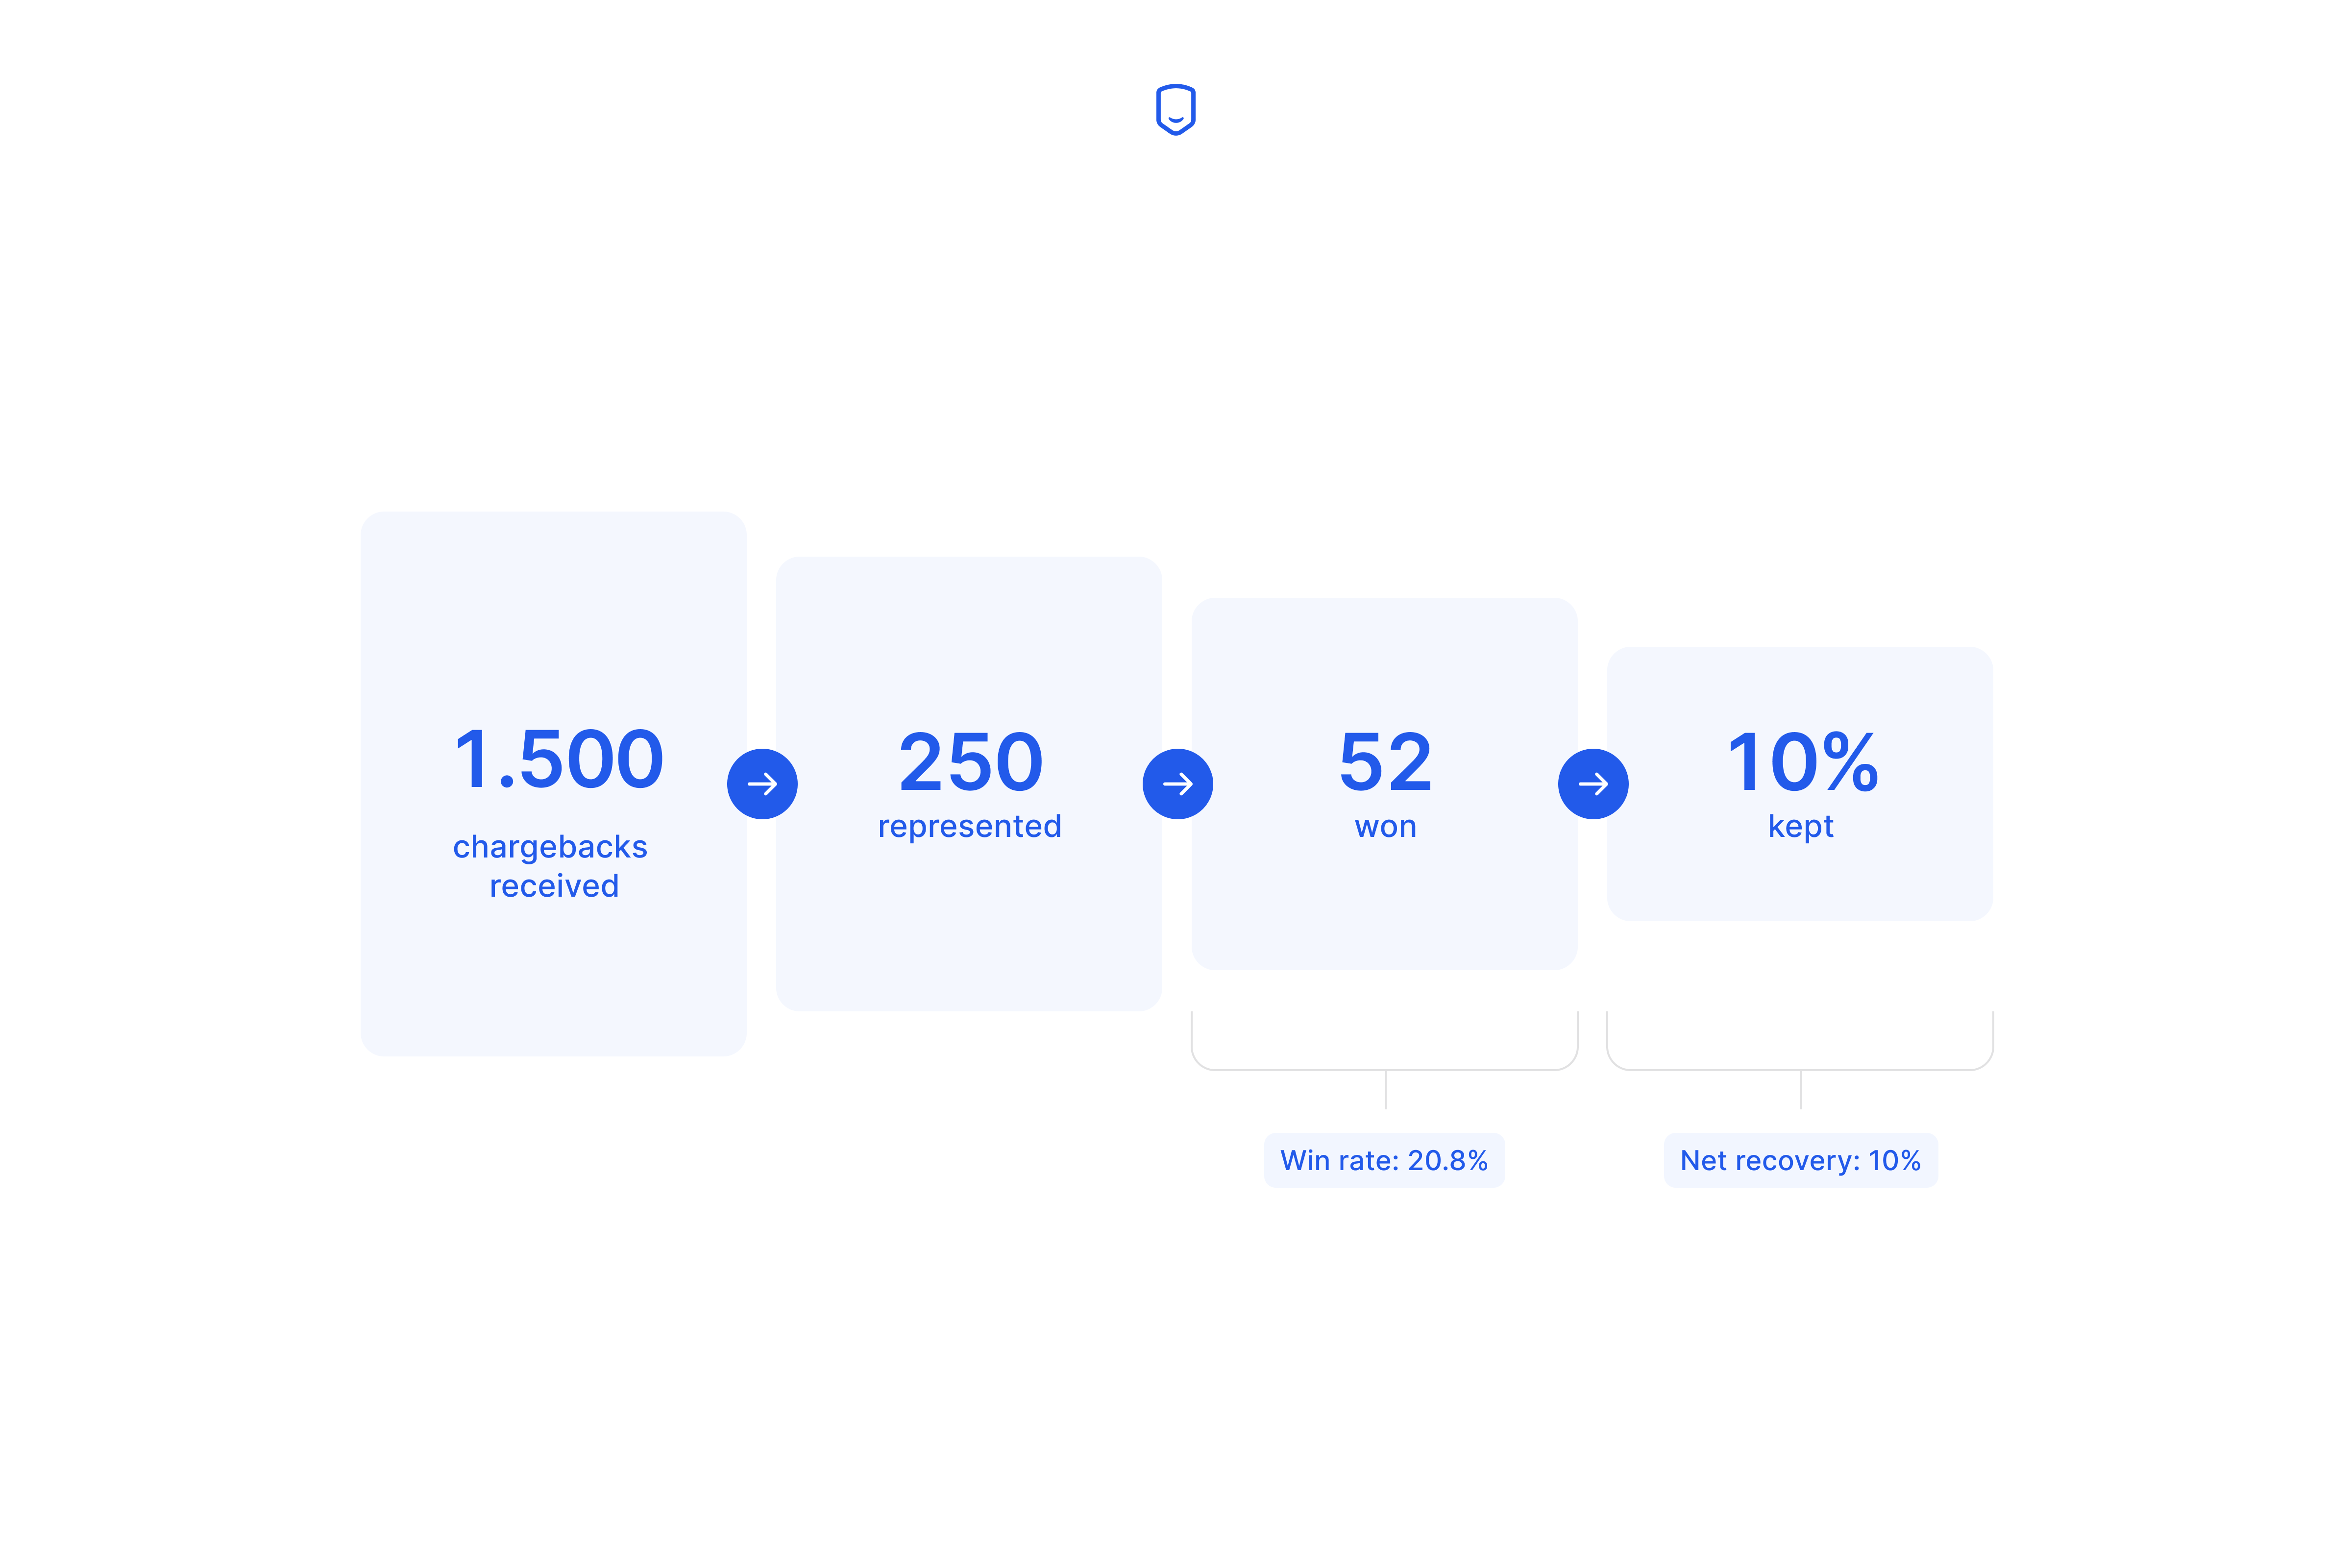
Picture a month with 500 chargebacks, of which you represent 250 and win 52. Your win rate is 20.8%.
Net recovery reads that same month against all 500. Count the 250 you left alone, the fees, and the hours behind those 52 wins.
You keep roughly 10%.
Run the fight-or-accept call on the net number. Run your own numbers with our ROI calculator.
A 20.8% win rate looks like a process problem worth fixing. A 10% net recovery rate tells you the cheaper money is in stopping disputes earlier.
How to improve your chargeback win rate
Read the reason code and build your file to it, submit inside your processor's cutoff, and catch disputes before they reach representment. Work them in that order:
- Read the reason code on the dispute notice and answer that question only.
- Log the cutoff date your processor sets, the day the dispute lands.
- Enroll in pre-dispute alerts so you can refund before a case is filed.
Reason-code matching is the one merchants get wrong most often. Our guide to why chargebacks happen maps the common complaints back to the codes they arrive under.
Deadlines cost the least to fix, because the failure is usually a missed date rather than missing evidence.
Alerts change the problem instead of the packet. Our chargeback alert coverage explains how the card networks' pre-dispute programs reach you in time to refund the customer.
That last one has a hard edge. An alert only helps in the window before a dispute is filed. Once a case reaches representment, better evidence and a faster response are all that change the outcome.
FAQ
Do merchants usually fight chargebacks?
Merchants contest roughly half the chargebacks they receive in the US. The rest get written off, mostly low-value cases where staff time costs more than the charge.
Is there an "ideal" chargeback win rate to aim for?
No published benchmark defines a target rate. Track your own trend instead, and treat a sudden jump as a sign you fought fewer cases rather than better ones.
Should a merchant fight every chargeback, even a small one?
No. Work out what an hour of your team's time costs, compare it to the charge amount, and write off anything below that line without reading it twice.
Does chargeback history affect future win rates?
Not directly, since issuers decide each case on the evidence submitted for that transaction. A rising dispute ratio does affect your standing with your acquirer, which is a separate problem from winning cases.