
What the MATCH List (TMF) Is and How to Get Off It


The MATCH list (Mastercard's Terminated Merchant File, or TMF) is a shared database that flags merchants terminated by a payment processor for excessive chargebacks, fraud, or rule violations. Being listed makes it extremely difficult to get approved for a new merchant account anywhere for five years.
I've worked chargeback support tickets where a merchant's first sign of trouble wasn't a warning. It was a rejected application from a brand-new processor who wouldn't say why. That's usually MATCH.
This guide covers the exact numbers behind a listing, the reasons merchants land on it, and the narrow paths off one. You won't be left guessing, or paying someone else to guess for you.
Key takeaways
What is the MATCH list (TMF)?
The MATCH list is Mastercard's Terminated Merchant File. It's a shared database listing merchants a processor terminated for chargebacks, fraud, or rule breaks. Mastercard requires every acquirer in its network to screen new applicants against it.
That's why a termination with one processor becomes a red flag everywhere else a merchant applies.
That's the part merchants underestimate. A listing stands for as long as the term runs, regardless of which processor applies to next.
Being listed carries direct consequences beyond the rejection itself:
- Near-automatic rejection at other processors, since most mainstream acquirers won't knowingly board a MATCH-listed merchant.
- Higher costs if you do get approved somewhere, because the processor is pricing in the same risk that got you terminated.
- A reserve hold that ties up your cash, often a percentage of your processing volume held back for months.
A reserve hold exists because the new processor takes on your risk the moment they approve you, and a riskier bet needs a bigger payout.
MATCH lists the merchant entity, and often its principals, not just one processing account. Opening a new account under a different business name doesn't clear a listing tied to the same owner.
Mastercard's file ties the termination to the people who ran the business. A processor can trace a new application back through shared ownership or a matching bank account.
MATCH vs. VMSS: the numeric thresholds compared
Mastercard lists you on MATCH at a 1% chargeback ratio, per Stripe's MATCH criteria. Visa's equivalent, VMSS, uses a higher 1.8% ratio and its own fraud math.
VMSS is also a terminated-merchant database, run independently by Visa. Your chargeback rate and fraud activity get measured against two separate sets of numbers.
Most merchant content online only ever covers one of them:
Both networks use these numbers to flag high-risk merchants before they approve them. The fraud row doesn't line up cleanly.
Mastercard counts a transaction minimum alongside a dollar figure. Visa's fraud trigger is a pure dollar threshold with no transaction floor.
A merchant running a high volume of small-dollar fraud can cross Mastercard's threshold first.
Say your store runs $40,000 a month in Mastercard sales, and $2,000 of that lands as chargebacks. That's a 5% ratio, five times over MATCH's 1% line.
The same $2,000 against $40,000 in Visa sales sits under VMSS's 1.8% line only if your dispute count also stays below 1,000.
The two lists aren't mutually exclusive, since each network only looks at its own transactions. A merchant with high dispute rates on both cards can land on both lists in the same month, since most merchants process both brands.
The minimums matter too. A store under MATCH's $5,000 floor stays safe even at a 5% ratio.
How do you find out if you're on the MATCH list?
Mastercard never tells you directly if you're listed. The first sign is almost always a rejected application from a new processor.
MATCH has no self-serve lookup for merchants. Only acquirers and processors can look up the list.
So you work backward from a rejection, or ask your processor to confirm it. A rejection alone tells you little on its own.
Look for signs that point specifically toward MATCH:
- A sudden, unexplained rejection. A new processor turns you down with no clear reason, when you'd normally expect a yes based on your revenue and history.
- A vague denial reason. The processor cites "risk" or "compliance" but names no specific issue on your application.
- A recent processor termination. A processor dropped you for chargebacks, fraud, or a compliance issue in the past five years, the exact window a listing would still be active.
- Multiple rejections in a row. Several processors turn you down back to back, which is unusual outside of a shared list flag.
- A request for heavy paperwork. A processor that does approve you asks for unusual financial history or a reserve, treating you like a high-risk merchant.
A vague denial is often how a processor phrases a MATCH hit without saying so. Ordinary declines rarely repeat identically across providers, but a MATCH hit does.
If two or more of these apply, ask your prior processor directly whether they filed a MATCH listing. They're in the best position to confirm it.
Why do merchants get listed on the MATCH list?
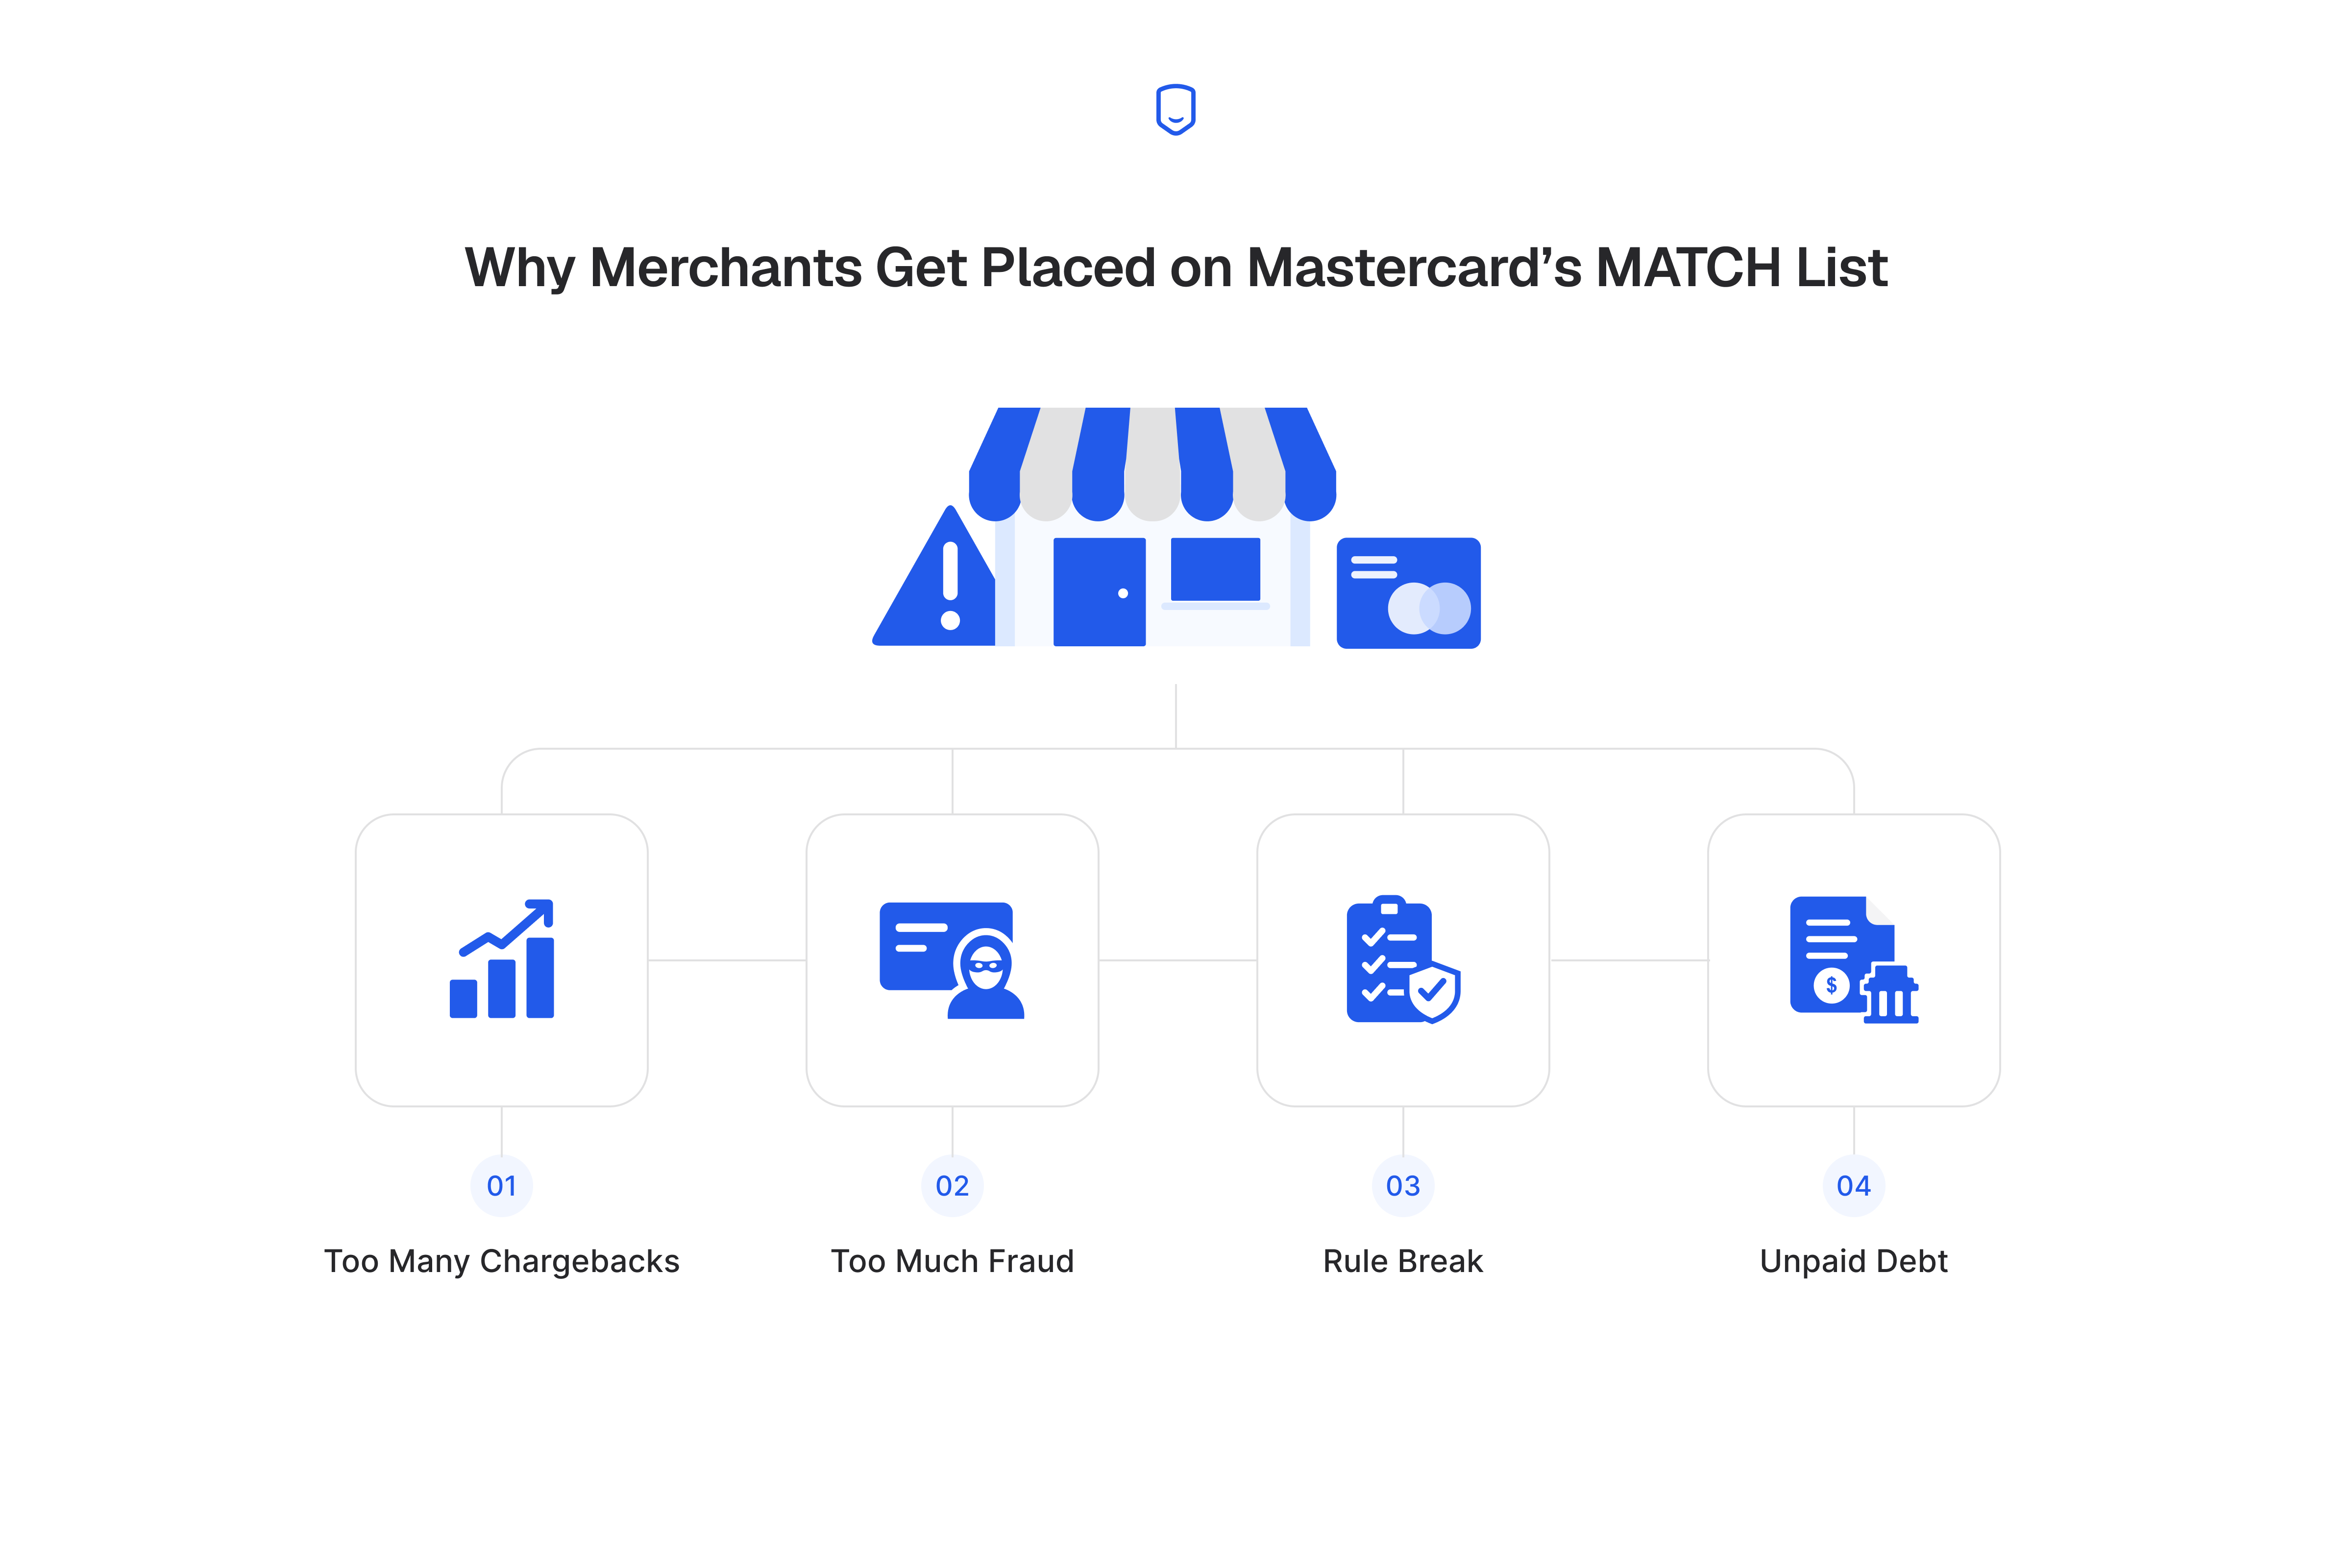
A listing traces to one of four reasons, and the reason decides which removal path applies later. They are:
- Too many chargebacks: your chargeback ratio and dollar total crossed Mastercard's line.
- Too much fraud: your fraud ratio, count, and dollar total crossed the fraud line.
- A rule break: you left a PCI-DSS compliance issue unresolved, or broke a different network rule.
- Unpaid debt: you left a balance owed to your processor when the account closed.
The chargeback reason means customers disputed charges often enough, and for enough money, to trip the threshold in a month.
The fraud reason usually points to weak screening rather than customer dissatisfaction. A rule break can be as narrow as processing a transaction type your agreement didn't cover.
Unpaid debt can hit even a merchant with a clean dispute history, since a large chargeback can wipe out an account balance on the way out.
A merchant can cross more than one line at once. Weak fraud screening drives up chargebacks too, since a stolen card eventually gets disputed.
Processors report a reason code when they submit a listing, and a removal request only checks whether the correction lines up with what was filed.
A processor can also list you in error, through a data-entry mistake or a listing meant for a different entity. That's the one case where removal looks more like a correction than an appeal.
A common business name raises this risk during manual review.
How long do you stay on the MATCH list?
A MATCH listing lasts five years from the termination date, regardless of the reason code. The five-year clock runs from when the terminating processor filed the listing.
It doesn't reset when you discover the listing or stop disputing it. It doesn't extend if you keep operating under the same ownership during those five years either.
A merchant who finds out about a listing two years in still has three years left, not a fresh five.
Merchants sometimes assume the clock starts when they first learn about the problem. Mastercard's clock only cares about the filing date.
Five years is a long time to run high-risk or offshore processing. Plan around it early.
If you know the reason code, and it isn't a processor error or a PCI-DSS fix, budget for the full term. Don't check back every few months hoping for an early exception.
Selling the business doesn't clear the clock either. The listing stays tied to the principals who ran it, so a new owner only gets a clean slate if the sale changes who controls the company.
Plan an exit during those five years, and expect a buyer's due diligence to surface the listing. Disclose it early instead.
Some merchants keep operating through the full five years on a high-risk processor. That path costs more per transaction, but it beats shutting down while you wait out the clock.
How do you get off the MATCH list?
Early removal works in exactly two cases. The listing was a processor error, or you've resolved the underlying PCI-DSS non-compliance that triggered it.
A listing for excessive chargebacks or fraud can't be appealed on the merits. It doesn't matter how good your explanation is or how much your business has improved since.
MATCH is Mastercard's record of your processor's own call to terminate you. The terminating processor, not Mastercard, has to submit the fix.
Mastercard only stores what the processor told it. Your real leverage is showing the processor's record is wrong, or that you've fixed what caused it:
- If the listing was a processor error: show the terminating processor proof of the mistake and request a correction.
- If the listing was for unresolved PCI-DSS non-compliance: complete a current assessment and ask the processor to confirm the fix.
- If neither applies: you wait out the full term, since no shortcut exists once a chargeback- or fraud-based listing is confirmed accurate.
Documentation matters for the processor-error path. Bring transaction records or account numbers that show the listing points at the wrong entity.
The PCI-DSS path takes longer, since a current assessment involves real audit work. Budget weeks rather than days.
Paying a "MATCH removal" service doesn't shorten that timeline. No legitimate removal channel exists for a chargeback- or fraud-based reason code, so at best you're paying for advice you could get for free.
How to avoid getting on the MATCH list
Staying under both MATCH's and VMSS's thresholds is the only reliable way to avoid either list. Resolve disputes before they post as chargebacks.
Ethoca alerts you to a Mastercard dispute before it posts, so it never touches MATCH's numerator.
Visa's RDR runs the same idea on Visa transactions, and it keeps a resolved dispute out of VMSS's numerator too.
A third option, CDRN, covers Visa dispute alerts as well. Enroll in whichever ones match where your customers hold cards.
The first thing I check on a merchant's chargeback problem is the billing descriptor. On my own stores, fixing what customers saw on their statement did more than any alert ever did.
A charge nobody recognizes is a chargeback waiting to happen. The customer sees an unfamiliar charge and calls their bank, and the bank files a dispute before the customer thinks to contact you.
Alerts reduce your ratio exposure, but they don't erase it. Fix the root cause too if your chargebacks or fraud already sit past MATCH's or VMSS's line.
A clearer billing descriptor helps, and tighter fraud checks help too. See our alert network data for how coverage splits by network.
Small merchants often skip fraud screening because it feels like overhead. A single bad month of stolen-card orders can push you past MATCH's fraud ratio fast.
Run your own ratio through our ROI calculator to see how much room you actually have.
FAQ
Can I check the MATCH list myself before applying?
No public, self-serve MATCH lookup exists for merchants. The closest you can get is asking a prior processor directly whether they filed a listing.
Can I get a new merchant account while on the MATCH list?
Mainstream processors reject you automatically. A high-risk processor may still say yes, usually at a higher cost, a reserve, or both.
Does a new business name remove a MATCH listing?
No. A listing follows the merchant entity and its principals rather than the business name or the processing account.
If I'm not on MATCH, can I still be on Visa's VMSS?
Yes, since the two lists are independent. A merchant with clean Mastercard volume but a high Visa ratio can be flagged for VMSS without ever appearing on MATCH.
