Friendly Fraud Prevention: 7 Ways to Stop It

Friendly fraud prevention starts with stopping the dispute before it becomes a chargeback. Fix the billing descriptor customers don't recognize, and add real-time dispute alerts. Those alerts let you refund or contest a transaction before the bank forces it back. Neither step slows down checkout.
I've lowered my own chargeback rate before I ever touched a dispute, by fixing the descriptor and turning on alerts. The system rewards fighting disputes after the fact, but the cheapest chargeback is the one the customer never files.
The tactics below can cut friendly fraud disputes. Refund-based prevention gives up the sale to avoid a chargeback.
How do you prevent friendly fraud?
Friendly fraud prevention works in two layers. One removes the reasons a charge looks unfamiliar, and one catches disputes with alerts before they become chargebacks. The two layers act at different times, which lets them work without touching checkout.
Descriptor, policy, and support fixes come first. They act before a dispute is filed, so fewer customers reach for the dispute button. Alerts come second, after the dispute but before the bank finalizes the chargeback. That gap is your chance to refund or contest it.
Neither layer adds a checkout step. Fraud-detection software works the other way, screening transactions before purchase, and that screen can block good buyers.
Both layers can reduce friendly fraud, where the cardholder made the purchase and disputes it anyway. Alerts can also flag true fraud, such as a stranger using a stolen card, so you can refund the payment or stop fulfillment. Keep fraud-detection tools in place to screen orders before purchase.
What is friendly fraud?
Friendly fraud is when a customer mistakenly or deliberately disputes a valid charge for a purchase they made. It differs from true fraud because the cardholder authorized the purchase. Receiving an order alone doesn't make a dispute friendly fraud. Defective goods, duplicate charges, and missing refunds can still give the customer a valid reason to dispute it.
The line between friendly fraud, chargeback fraud, and true fraud decides which fix you reach for.
Our guide to what friendly fraud is draws that line in full.
What friendly fraud actually costs merchants
A single friendly fraud dispute costs a US merchant at least the $15 Stripe dispute fee, plus the lost product and any staff time to respond. That is before you count the revenue from the original sale, which is also gone.
The cost compounds because most disputes trace to a few fixable causes. In our dataset, cancelled-recurring transactions (reason code 13.2) run 8.5% of alerts, and cancelled-merchandise or services (13.7) run 8.2%.
Across the roughly 1.1 million alerts with a recorded reason code, those two rank second and third. Only card-absent fraud is bigger.
So one fix heads off many disputes at once. A clear descriptor plus a clear cancellation confirmation covers both of the top two.
The per-dispute number is the direct cost only. It leaves out the compounding cost of a rising chargeback rate. A higher rate triggers reserve holds from your processor, and it risks landing you in a card-network monitoring program.
At scale, that is a bigger threat than any single dispute.
Run your own numbers with our ROI calculator.
The 7-Tactic Friendly Fraud Checklist
Seven tactics prevent friendly fraud, ranked by how directly they stop a dispute from being filed or escalating to a chargeback. They split into two groups.
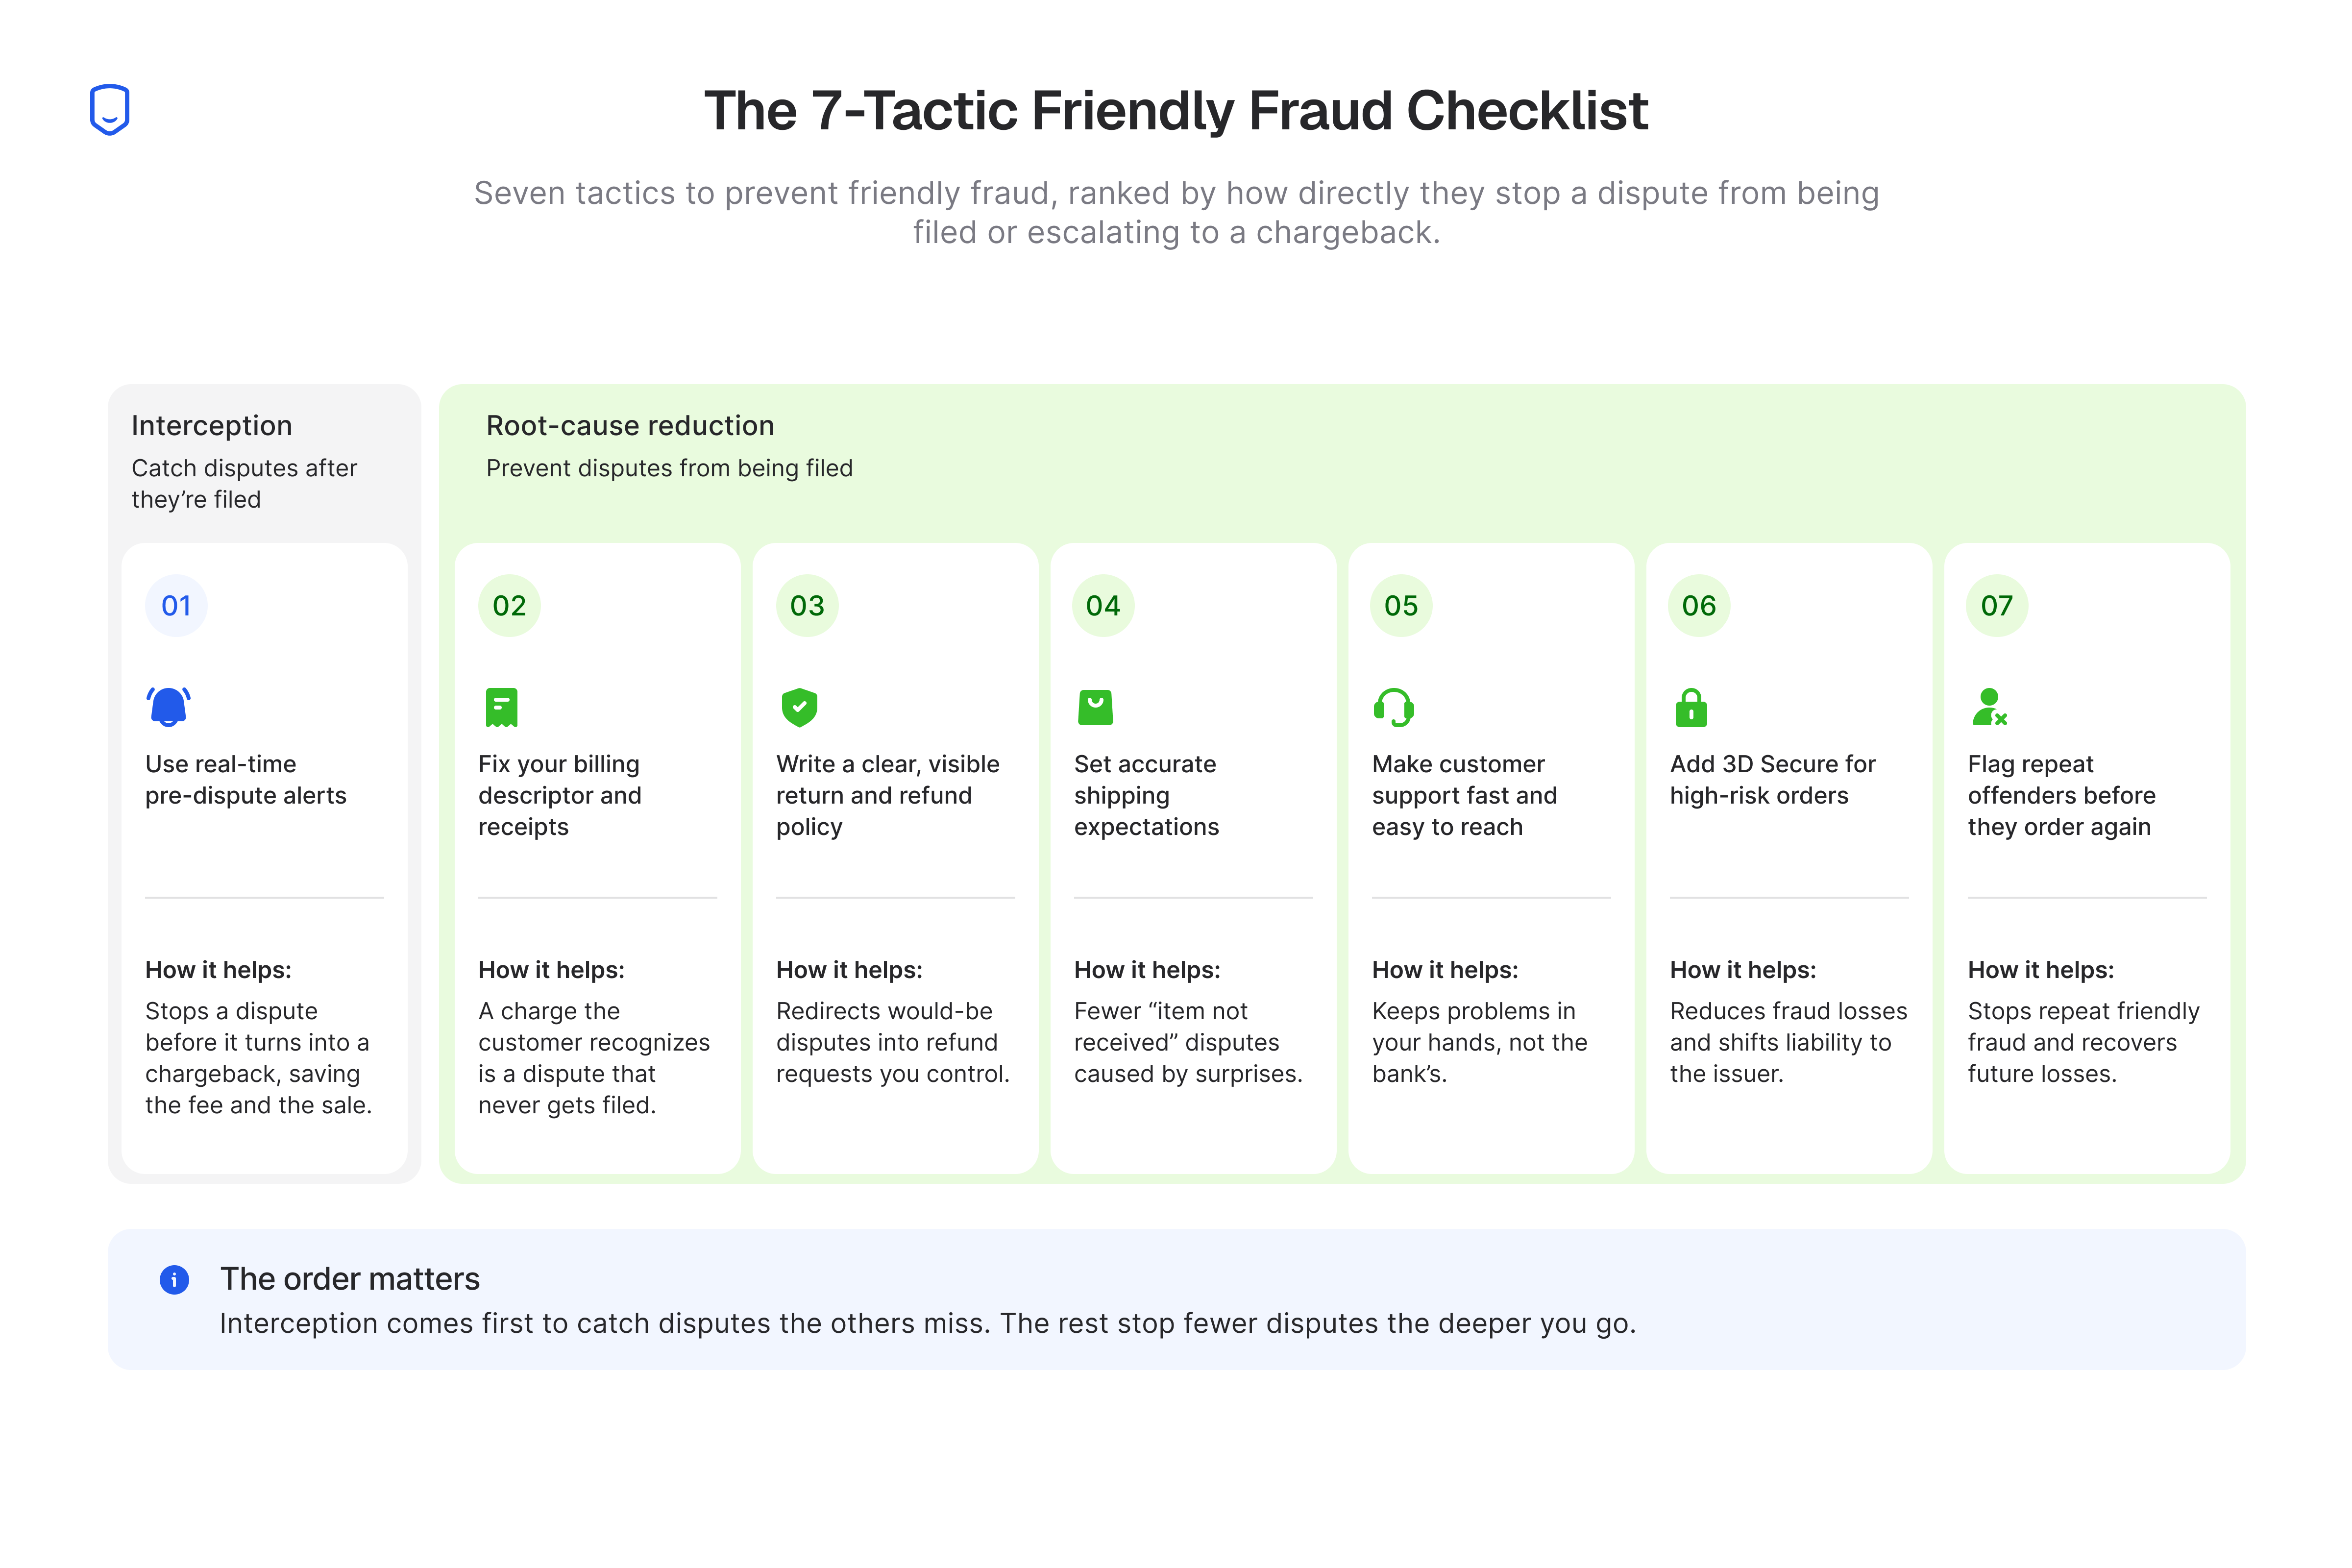
The first group is alert-based interception. Tactic 1 stops a dispute after it is filed but before it becomes a chargeback. The second group is root-cause reduction. Tactics 2 through 7 cut how often a dispute gets filed at all.
The order puts interception first, because it catches disputes the other six miss. From there the fixes descend by how much leverage each one carries.
1. Use real-time pre-dispute alerts
Real-time dispute alerts catch a dispute the moment a customer files it. That gives you a short window to refund or resolve the transaction before the bank finalizes a chargeback. Once the chargeback finalizes, you pay the fee and lose the sale.
Refund it inside the window and you can avoid the chargeback and its fee. The refund still returns the sale amount to the customer.
The alert reaches you through the card networks' own dispute programs. It fires only on transactions a customer has already disputed, so it leaves checkout and conversion untouched. The catch happens after the customer buys and then reaches for a dispute.
Our guide to how alert-based prevention works walks through how the networks connect and decide a dispute.
We offer real-time alerts across the major networks with auto-refund built in.
Set up real-time dispute alerts so a dispute resolves before it ever costs you a chargeback fee.
2. Fix your billing descriptor and receipts
Most friendly fraud starts with a charge the customer doesn't recognize, so a clear billing descriptor is the fix that helps most. The descriptor is the text a customer sees on their bank statement.
When it shows a legal entity name or a random string, the charge reads as unfamiliar. An unfamiliar charge often turns into a dispute.
I've been on the customer side of this too. I once looked at my bank statement and saw a charge I couldn't place, and I nearly filed a chargeback on the spot. A little digging showed it was a legitimate purchase I'd forgotten, hidden under a descriptor that didn't match the brand.
A good descriptor removes that reflex, because the customer recognizes the name and never reaches for the dispute button.
Make the descriptor match the brand the customer bought from. Add a support phone number or URL where the format allows, and send an itemized receipt with the same name at the top. The billing descriptor is what the customer checks first, so it is where recognition starts.
3. Write a clear, visible return and refund policy
A return and refund policy that a customer can find and understand redirects a would-be dispute into a refund request you control. When the path to a refund is obvious, most reasonable customers take it. It is faster than calling the bank, and it works.
Put the policy on the product page, in the checkout flow, and in the order confirmation email. Keep it in plain language a busy shopper reads in one pass. Bury it in a footer link and you hand the customer a reason to skip you and call the issuer.
4. Set accurate shipping expectations
Disputes spike when a customer expects an order sooner than it arrives, so state real shipping and handling times before checkout. A buyer who thinks an item is late suspects something went wrong. "Item not received" is a common friendly fraud reason.
Show the handling window and the delivery estimate on the product page, and repeat them in the confirmation email. If a shipment runs late, send a proactive update with tracking. A customer who knows where the order is doesn't dispute it.
5. Make customer support fast and easy to reach
When support is fast and easy to find, the customer brings the problem to you and the resolution stays in your hands. Every dispute on a legitimate charge is a support conversation that didn't happen, or happened too slowly.
Put a real contact method one click from the order confirmation and the top of your site. Answer quickly. The longer a frustrated customer waits, the more attractive the dispute button looks, because the bank feels faster than you do.
6. Add 3D Secure for high-risk orders
3D Secure adds issuer-verified authentication that can shift liability for certain fraud disputes away from you. Use it when your processor, the issuer, or applicable rules require it, and consider it for high-risk orders too. Some payments authenticate without an extra customer step.
That deters some abuse, and it shifts who pays for the fraud toward the bank when a dispute comes.
The tradeoff is friction.
An extra authentication challenge can cost you a sale. Use risk-based rules where authentication is optional, such as for a first-time high-value buyer or a mismatched shipping address. Keep required authentication in place for routine orders too.
7. Flag repeat offenders before they order again
Some customers dispute again and again, so keep a block list and stop the repeat disputers before they check out a second time. A buyer who filed a friendly fraud dispute last time is far more likely to file another.
Record the details of confirmed friendly fraud cases, then screen new orders against that list. This tactic works after the fact. It only pays off once you've already absorbed a first dispute from that customer. Treat it as cleanup that reduces the risk of more losses from the same customer.
Friendly fraud in subscriptions: the forgotten charge
Subscription merchants face a friendly fraud pattern of their own, where a customer disputes a renewal charge they forgot they had agreed to. The renewal arrives on a schedule the customer set months ago and stopped thinking about.
This happens because the renewal often shows up with no reminder and a descriptor that doesn't match the product name. The charge reads as a mystery instead of a subscription the customer chose, so the dispute follows.
A pre-renewal reminder email and a subscription-specific descriptor fix most of this. They still leave the customer who wants to cancel and disputes rather than using your cancel flow. That case needs a working self-serve cancel path.
The customer wants to leave, and the dispute is only the tool they reached for.
When to fight vs. refund a friendly fraud chargeback
Refund disputes below a set dollar threshold automatically, and fight only the disputes above it where your evidence clearly supports the sale. This split keeps small disputes cheap. It reserves your time for the ones worth contesting.
The threshold exists because fighting a small dispute costs more than it saves. Assembling delivery confirmation, support history, and order records takes staff time.
On a low-dollar dispute, that time is worth more than the amount you'd recover. A larger dispute justifies the effort, but only when you hold the evidence to win.
In Chargeback.io's Tim's Coffee case study, the merchant set the line at $300. Anything under it got an automatic refund, and disputes over it went to a manual fight. That single rule was simple enough to run without a dedicated dispute team.
Fighting only works when representment evidence is realistically winnable. A merchant with no delivery confirmation, no order records, or a vague return policy should skip the fight at any threshold. A lost fight costs the dispute fee on top of the original loss.
Where prevention hits its limit
Prevention tactics reduce friendly fraud, they don't eliminate it, because some disputes come from payment paths these tools can't fully see. A handful of disputes will still reach you. So plan for a residual rate and name where it comes from.
Tokenized wallet transactions like Apple Pay, Google Pay, and Stripe Link are harder to match back to the order. An alert can't always link the dispute to the sale. Some issuers also skip the alert networks and file a chargeback directly, with no warning at all.
In Chargeback.io's Dropship.io case study, alerts cut the dispute rate from 0.93% to 0.16%. That is roughly a 78% reduction in dispute count. The gaps that remained were the two named above, tokenized wallet matching and issuers that bypass alerts.
That gap widens over time. Digital wallets ran 40% of US e-commerce transactions in 2025, projected to reach 44% by 2030. As wallets grow, the share of transactions these gaps affect grows with them.
How we sourced our data
The reason-code figures here come from Chargeback.io's own platform alert data, across the alerts we processed for enrolled merchants. We counted total alerts in each category and report them as shares of the labeled total. Every percentage covers only alerts with a recorded reason code.
The numbers are anonymized and aggregated. They describe our own platform, so read them as our slice of the market.
FAQ
Is friendly fraud illegal?
Yes, disputing a charge you know is legitimate is a form of fraud and can carry legal consequences, though issuers rarely pursue small cases. In practice, the customer usually risks a closed account or a block list.
How do I know if a chargeback is friendly fraud?
It may be friendly fraud when the cardholder disputes a valid purchase they made and received. Check the complaint against your order, delivery, and support records first. Delivery confirmation alone doesn't rule out a defective item, duplicate charge, or missing refund.
Can a customer commit friendly fraud without meaning to?
Yes, plenty of friendly fraud is unintentional, a forgotten subscription or an unrecognized descriptor rather than deliberate abuse. Descriptor and reminder fixes work so well because they remove the confusion before it becomes a dispute.
Does a dispute hurt the customer's credit?
No, a chargeback doesn't appear on a credit report or directly affect a credit score. The consequence a customer risks sits with the merchant and their own bank, such as a closed account.